Software
Houzz Logo Print
faron79

Gosh!! My retirement?!

3 months ago

Holy Moley!!
Can it be!? On 12/31 this year, it'll be official. Working thru the year 2026, then hanging it up.
This way, I can capture our company's full 2026 valuation. I'll be 65 in September....UFFDA! I can't rule out asking some ?'s here about Medicare, SS, & other "winding it down" issues.
I'm fortunate.....before taxes, it'll be over the $1.5M mark. So, we're working with Insurance & Financial people to smartly transition the $$$. Together with DW's accounts, I THINK we'll be fairly comfortable.
AND.....I think DW's resistance to something totally impractical with a V8 & big tires.....is crumbling!!! 🤪😇🥰
Then again......an Escalade "V" (very rumbly!) is more roomy & "practical".....isn't it??? 🙃😉

Comments (35)

  • 3 months ago

    Congratulations! Retiring was the best career move I ever made! I'm sure you'll enjoy it, and I'm glad you're preparing financially ahead of time.

    Faron79 thanked Annie Deighnaugh
  • 3 months ago

    Very exciting - congratulations! Hopefully we'll hear more from you when you have more free time.

  • 3 months ago

    Congratulations! I've enjoyed every day of my retirement and I hope you do too!


  • 3 months ago

    Congratulations!

  • 3 months ago

    Remember the old saying, "we married for life, not for lunch" and give your spouse space and time of their own.

  • 3 months ago

    Congratulatons!

  • 3 months ago

    Great news Faron! Now you have 6 months to figure out all that Medicare, SS stuff. It isn't easy.

  • 3 months ago

    Congratulations!

  • 3 months ago

    Congratulations Faron! I retired young and am just now dealing with some of these things myself. I love retirement and bet you do too!

  • 3 months ago

    Congratulations, Faron!

  • 3 months ago

    Congratulations. I was just asking a friend who retired one year ago if she was happy with her decision. She said she wishes she could have retired even earlier.

  • 3 months ago
    last modified: 3 months ago

    Great to hear from you and Congratulations! You will be glad you did.

    It sounds like you are getting well-prepared. Navigating Medicare and all the associated offerings can be daunting. I’ll just say that most of the people i know do not like the Medicare Advantage programs. There are usually some qualified Medicare advisors (some work for free in Senior Centers, etc) that do not represent some insurance company. That would be my recommendation to you and your wife to start searching for someone and have them look at your current finances and what sort of plan beyond Parts A and B will work best for you.

  • 3 months ago

    Congratulations, Faron!

  • 3 months ago

    Medicare advisors are the best. Don't do anything until you talk to one. Free. No sales at all. Call your closest County Office of Aging )or whatever they call it). Basic Medicare plus a supplement is the way to go.

  • 3 months ago

    Hi Faron ! The best times are a-comin’ :) Good luck and drop in more often now!!

  • 3 months ago

    Now we know we are old when “ the baby’ of the group is retiring!😀

  • 3 months ago

    Congratulations,Faron!

  • 3 months ago

    Congrats, Faron. :)

  • 3 months ago

    Congratulations!

  • 3 months ago

    Congratulations! I just retired 2 weeks ago (Turn 65 in June).

    I retired from United Health Care where I worked as a data analyst within the Medicare arena.


    I am not a Medicare Consultant, but I did learn something over the past 20 years and learned more while navigating my choices and helping several other people navigate their choices.


    PLEASE NOTE - I have work experience with Medicare but I am not a licensed broker or consultant and am providing this information as general information and not professional advice.


    You will sign up for Medicare Part A and Part B through Social Security.


    Now you have to decide which plan you are going to get to cover what traditional Part A and Part B coverage doesn't include. (covers 80% of charges after the annual deductible).


    Every County in each State has different offerings at different price points, so you do need to compare what is available where you live, but the good part is that core coverage is dictated by the Federal Government. 5 companies may offer a particular plan, but the core coverage is the same for all 5.


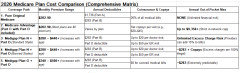
    This chart shows the basic differences between the most common plans and compared to traditional (A+B) coverage including Part D prescription medication coverage for the Advantage (usually included) and Gap plans (not included).


    Note: Some states have made it illegal for doctors to charge excess fees over Medicare Standard charges which is why I included a banned state and standard state option for Plan N


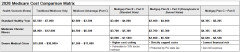
    This chart gives you some standard spending numbers that you can compare based on some tiered medical condition costs.


    Some things to keep in mind - You only get the guaranteed age based rates for Plan N and Plan G during your initial enrolment period. If you choose traditional Medicare or an Advantage Plan and then decide to switch to a Gap plan the premiums will be adjusted based on your medical history. You can always change from a Gap Plan (G/N) to an Advantage Plan without a health screening.


    This is where you need to evaluate your health history, your family history, your aversion to risk and special circumstances that may alter your numbers (Retired from a job that covers all or part of your insurance premium once retired or low income status. . . )


    I have already had a heart attack and cancer and have reached my Out of Pocket Maximum 4 times in the past 10 years and I have some moderate chronic conditions that require monitoring. I assumed 3 years with a major medical issue and 7 years with a moderate chronic condition to make my decision on type of coverage. Plan N w Part D was the best option for me.


    I then evaluated the Plan N options using the average published costs for age 65 through 75 and a comparison of the same costs from 5 years ago that I got from my Medicare Consultant.

    I compared the options for Mutual of Omaha, United Health Care, Aetna, Humana and the Blues.


    Different companies offered Household or Spousal Discounts of 5-12% that did not impact my costs, but did impact some of the people who I assisted with their selection.


    For me, Humana had the lowest cost, but it was not a substantial savings over Aetna. Aetna's rates had increased at a slower rate and they have a better rating for both financial stability and customer service than Humana.


    My cost is $282.50 per month for Plan A/B - $123 per month for Plan N and $8 per month for Part D coverage for a total of $413 per month. More than I would like to spend, but the most affordable, long term option for me.


    One other thing to note: Medicare Consultants do not charge you anything, but they do work on commission. Ethically, they should be finding the best plan for you, but they make a lot more money selling advantage plans than Gap Plans.


    The Centers for Medicare & Medicaid Services (CMS) sets the maximum allowable compensation agents can earn for Medicare Advantage and Prescription Drug Plans

    Medicare Advantage (Part C)

    • National Baseline: $694 initial and $347 for renewals.
    • Connecticut, Pennsylvania, & DC: $781 initial and $391 for renewals.
    • California & New Jersey: $864 initial and $432 for renewals.

    Medicare Part D (PDP)

    • National Baseline: $114 initial and $57 for renewals.

    Medicare Supplement (Medigap)

    • Commissions: These plans are not regulated by CMS, allowing private insurance carriers to set their own rates. Agents typically earn around 20% to 22% of the annual premium for new policies, with lower renewal commissions (usually for up to 6 years).

    My consultant earned $295 + $114 on my plan N and part D ($409 total) Had I bought an advantage plan he would have been paid $781 for the Advantage Plan that includes Part D.


    PLEASE NOTE - I have work experience with Medicare but I am not a licensed broker or consultant and am providing this information as general information and not professional advice.

  • 3 months ago

    Congratulations! I retired last September (turned 65 last August). I honestly have no idea what I do all day but the days fly by and I am just so happy. I still pinch myself in the mornings when I don't have to log in to work and deal with the nonsense and politics. Total bliss. I'm sure you too will enjoy every minute!

    I did get a 1 year package so I am still getting paid and have full benefits until October this year. I just this morning emailed the HR department. They told me to email them a few months before my package ran out to sign up for Medicare plan B. Signed up for plan A last October. So I will also be navigating what the best supplemental plan is. I also have to figure out what we'll do for DH. He doesnt' have benefits at his company (which consists of 2 people!), and he doesn't turn 65 until 2027. We'll probably just do COBRA for him for the 10 months until he turns 65.

    Here's something that makes no sense to me -- I can use HSA funds (of which I have a lot) to pay for COBRA but cannot use those funds to purchase insurance on the market. Our government has the strangest rules and makes things so complicated.

  • 3 months ago

    Woohoo! Congratualtions, Faron. Retirement is a delightful thing.


    ps. No pics of the pup?

    Faron79 thanked cyn427 (z. 7, N. VA)
  • 3 months ago
    last modified: 3 months ago

    Jennifer Hogan, Medicare consultant with your local agency o aging, called SHIP in some places, there are many names. But they are not associated with any sales, not investment companies, banks, insurance companies, etc. Totally free and independent. Insurance agents or 'consultants' will earn money, your local SHIP is often a trained volunteer.

    https://www.shiphelp.org/

    You gave great info. My background is with two different county agencies on aging.

  • 3 months ago
    last modified: 3 months ago

    @sushipup2 - You are correct that SHIP is not associated with sales and can and do provide solid foundational information on the various available plans. Nothing wrong with them, but I look at them more like taking a Medicare 101 class vs deep dives. Not all paid consultants are good with the deep dives or analysis piece, but some are very good. There is also some benefit to having a consultant sign you up for your benefits - they have records of when it was submitted and can push things if something goes sideways or help with things like appeals. The volunteers are not allowed to do this - they can only guide you, can't actually do anything for you.

    I do find that the volunteer free services are often more well versed in helping people navigate the complexities of a dual Medicare/Medicaid plans and other available benefits for low income seniors.

  • 3 months ago

    HSAs actually exclude using the money to pay insurance premiums. It is designed to pay for out of pocket medical expenses, but over the years we got a lot of exceptions including COBRA premiums and Medicare, premiums with the exception of Medi Gap plans.

  • 3 months ago

    hmmm i dont think Faron is the baby. We have a few youngsters!

    Faron79 thanked Tina Marie
  • 3 months ago

    HSAs actually exclude using the money to pay insurance premiums

    Yes, that's what I said. Makes no sense. Not a big deal since we'll probably just do COBRA since it's the easiest, even if more expensive. And using pre-tax money probably makes it a wash anyway. I just find these rules with no logic very annoying.

  • 3 months ago
    last modified: 3 months ago

    Congrats on your retirement. Be sure to check out Wellcare for RX plan options. My sister and a friend both have through the company.

  • 3 months ago

    I found SHIP service invaluable. My husband retired before me. He was driving me nuts with all the options from this broker and that broker. I went for a counseling session with a volunteer (I think I was very lucky with who I got that day?), and I made the decision for us very quickly. The only advice she gave me: choose the VERY, VERY BEST medical plan that you can afford; it's difficult to later change medical plans despite what they say? Pharmacy plans are much easier to change.

  • 3 months ago

    Wow!

    You guys rock!!!

    Lotsa info to digest, that's for DAMN sure. I'll be meeting soon with an Insurance planner that frequently deals with people retiring from the Retailer that I'm at.


    I'll see about some Collie pics! 🐶


    Faron

  • 3 months ago

    One more nate: I am busier post retirement than when I worked! Everuone said I would get bored. . . Not a chance!

  • 3 months ago

    Here's more advice: If you want to do something, do it now. Don't put it off. We will both be 79 soon, and Jim is now using a walker and has macular degeneration. I have arthritis. Our travel days are behind us. We moved cross country 10 years ago; there is no way we could do it today. We only get out of the house to shop (just me), see doctors, and we have dinner and lunch out at least once a week (only places with handicap access, no street parking, etc.).

    Don't put anything off, do it now.

    Faron79 thanked sushipup2
  • 3 months ago

    sushipup is right. We retired exactly a year ago at 60 and read a lot about retirement before we took the leap. We have taken the advice that the next 10-15 years are our go-go years and filled our first year with new adventures and getting ourselves in good physical shape.


    One thing I've found personally to be very helpful is keeping a retirement journal. Everyday, I write down the date (this is important!) and what I want to do that day (I almost never accomplish everything, but still .. ). I also write down 3 things I'm grateful for. These don't have to be major things. For example, after a big wind last night, one of the things that I'm grateful for this morning is that the new birdhouses and their residents didn't blow out of the trees last night.


    Another thing sushipup is right about is giving your spouse space. My MIL told my DH this, he's read about it, I've reminded him, I've explained how it will make us closer in the long run and prevent petty conflicts and that it doesn't mean i don't love him, but my usually sensitive DH cannot wrap his mind around why we might need even a few hours apart. Driving me nuts, but grateful he's here to do so. Haha

    Faron79 thanked daisychain011
  • 3 months ago

    I agree with the do it now mind set. Or at least, I'm trying to. DH keeps telling me we need to do it now while we can. And I mostly agree, but I also worry about running out of money. DH and financial advisor tell me we're fine. But I still worry. We bought an annuity to quiet some of my fears. It helped but I still worry. DH is constantly pushing me to book more vacations. It's a struggle.

    Faron79 thanked jsk
Sponsored
Haus Studio
Average rating: 4.8 out of 5 stars28 Reviews
Franklin County's Preferred Custom Cabinetry & Design Studio