Software
Houzz Logo Print
christen_hellums

HELP! Builder says porch might be a $$ problem

6 years ago
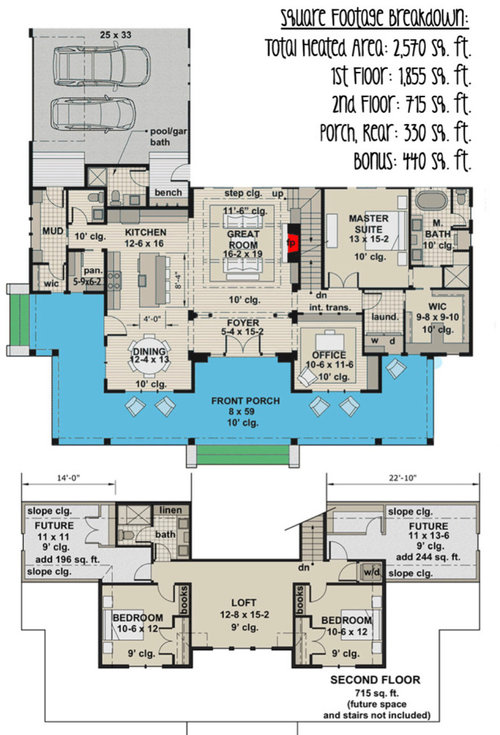

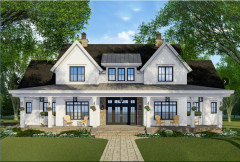
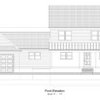
Here’s the deal...We are about to purchase the plans to build our house and before we spend $2000+ on them we sent our builder a pic to get an idea of how much it would be to build. He came back and said that we needed to be concerned about the large front porch because the bank will only give us 85% of the appraised heated/cooled square footage of the house. So that means we would have to come out of pocket for the porch?? Which he quoted $45,000?? Does the bank really not consider porches and carports/garages to be part of the appraisal?? Good Lord! And not only that, I would be SICK knowing I spent that much money on plans we couldn’t even use!Would love to hear from those who have built homes with large porches and also those who wanted to but couldn’t because of cost..

Comments (20)

  • 6 years ago

    Before you pay money for these plans I would consider a few things.

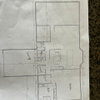
    1. There is no coat/storage closet.

    2. No window in your kitchen

    3. A guest bathroom right next to the kitchen can be a little awkward.

    4. If the laundry was a little wider you could flip the washer dryer and possibly add a sink or shelf etc.

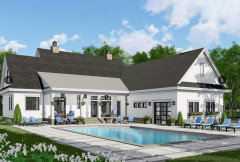
    5. Will you be building on acreage? If not do you see yourself utilizing such a big porch? Most people tend to hang out in their backyard so if you don't see yourself using it the money it might be wasted.

  • 6 years ago
    last modified: 6 years ago

    I have never seen a lender separate the living area value from the total building value to determine loan value. In any event, A S is right about checking your sources. Before you do anything check with the lender. If the lender is separating the values (living area from total area) then find another lender. The appraisal is one value, not a separate value for living areas and non-living areas. The lender works off of LTV (loan to value). Not all lenders are the same. This is especially true for construction loans.

    Jennifer C has excellent points.

    You would be far better off to have an architect work with you on a plan that works for your wants and needs on your lot. Buying an off the rack plan has pitfalls - not the least of which is the fact that the plans do not contain all the construction documents you need to build the house for your area (no matter where you are located). Find out from your building department what is needed and find out from your plan producer what they actually provide for the $2k cost to you (to start).

    The biggest pitfall in my opinion is you end up with a plan that doesn't work with your lot configuration or lot views. You end up going through the build and spending the time and money but don't get the best result. You end up with a stock plan type but have spent custom money to get there.

  • 6 years ago

    The bank should be appraising the entire build project... BUT, large porches can be VERY expensive without adding much value to the project, so yes, that might cause an issue.

  • 6 years ago
    last modified: 6 years ago

    Do you own the land currently or is that part of the loan?

    Construction loans are misunderstood a lot. Lenders usually have two caps in a construction loan, most people only see one of those caps which is loan to value (LTV), but they will also have a cost to build cap (note: land is usually considered a cost to build so you might think of it as cost to build plus land). The cost to build cap keeps people from doing cash out and some other things. Cost to build caps are usually higher than the LTV cap though they can be any amount. IIRC mine are typically 95%, and banks going to 100% is not unusual.

    To keep people from including hardscaping and outbuildings in their loan the bank will often limit the cost to build to heated square footage, or heated square footage plus garage, etc. This keeps the loan down to more recoverable items and stops people who build with equity from adding things until they use up the equity. Different banks do it differently, and some banks can get pretty flexible as you get more headroom in your appraisal and others are rigid no matter what.

    For most builds the cost to build cap is not really relevant. Since most custom homes appraise for less money than their cost to build plus land, these numbers rarely get discussed.

    An 85% cost to build is not particularly generous and would lead me to consider another lender.

  • PRO
    6 years ago

    Hi, Christen,

    Kudos to you for checking with your builder before purchasing plans of any kind.

    While it's difficult to estimate construction cost from a magazine study plan with good accuracy, features that add significantly to the construction cost such as large porches, huge garages, breezeways, footprints incompatible with the building envelope or site, etc. can be flagged as candidates for redesign or elimination. If you get a sufficiently long list of required changes or the anticipated cost of any feature(s) drive you over budget then the particular plan may not be a good basis for the design of your home.

  • 6 years ago

    I would reconsider the plan entirely. Except for the great room all spaces will be sorely lacking natural light.

  • PRO
    6 years ago

    Sit down with the lender, find out how much you can borrow, what percentage of value they lend and have them develop a work sheet showing the totals vs what they expect you to produce in cash or down payment. Vague percentages will lead to surprises, forgetting the closing costs, etc. They may require 20% down plus a reserve.


    In any event, lenders don't lend on specific items, they lend based on total value. If add a $20K folding door that only increases value by $5K (made up example), they only lend you the percentage of the 5K, etc.

  • 6 years ago

    Are you sure he isn’t just trying to discourage you from buying this plan without coming right out and saying it?

    The second floor of the home has sloped ceilings throughout. Do you realize how much that will impair the full use of the space? I have just a couple of small sloped ceilings on my second floor. Luckily they just minimally impacted my space. This plan has lots.

    i googled your plan and I can see why it appeals to you. Pretty! But I think you can do better.


  • 6 years ago

    My first thought is the contractor hasn’t built a house of this size or complexity before. Have you researched him? Have you seen homes he has built? Has your lender worked with him before? Is he new to the business? It is odd his objection is the cost of the porch as related to the overall cost. This seems to related to inexperience and inability.

  • 6 years ago

    Why do you like this house? I ask because the interior will be dark with little natural light.

  • 6 years ago

    I would just check with your bank first & go from there. I like the initial plan but would tweak it some, just personal preference.

  • PRO
    6 years ago

    @remodeling1840,


    I wouldn't infer that the builder is inexperienced. He/she is simply pointing out that the porch will contribute significantly to the overall cost. If the builder knows the client's budget and considers the porch to be a budget buster, then giving them a heads up before purchasing a $2,000 plan adds value.


    It's tough to infer the actual area of the porch, but the 8' x 59' dimensions would suggest at least 472 SF. That compares with 1855 SF indicated as conditioned living area on the 1st floor. I would consider to be a significant fraction of the 1st floor constructed area.


    By contrast, an inexperienced builder would let the client purchase the plan without mentioning anything. They would both get surprised later in the process.

  • 6 years ago

    Again, people often imagine a loan has a single cap. They usually do not...

    LOAN PURPOSE; OVERALL LOAN-TO-VALUE LIMITATION. The purpose of the Loan is to provide funds to enable Borrower to (i) purchase or finance the purchase of the Project Property, and (ii) undertake and complete the Project. Lender shall not be obligated to make Advances that exceed, in the aggregate, the lesser of (i) the Loan Amount, (ii) 90% of the Total Project Cost (as approved by Lender), or (iii) 80% of the final appraised value of the improved Project Property (as approved by Lender’s appraisal reviewers in their discretion).

    -----------------

    (ii) the "as approved by the lender" may be heated square footage if they want it to be that.

  • 6 years ago

    I won't answer this question as a retired appraiser, rather as a person who has been in your shoes.

    Porches are very expensive to build. They have framing structure, ceilings, floors and trim. That means that the space is expensive relative to its value.

    A porch will be valued at a much lower rate per square foot than a heated and air-conditioned space.

    While we all love porches, they cost a lot and provide little additional valuation to the structure. That's the simple explanation.

    It was a really good idea to have a meeting with the lender and the builder before you take the leap. You've saved yourself a lot of trouble and expense.

  • 6 years ago

    Charles Ross- my parents were told by a contractor he couldn’t build s four bedroom home, three bedrooms were his limit! In the interest of full disclosure, I was a sub for 32 years. I have heard it all.

  • 6 years ago

    Remodeling1984, I can top that. We had builder that told one of the homebuyers in his project that he couldn't install any windows that were round or arched. He could only install rectangles.

  • 6 years ago

    Homechef59 I can't stop laughing! Truth is stranger than fiction!

  • 6 years ago

    More full disclosure-I had a wrap-around porch on the house we built 20 years ago, so I do know it really adds to the cost. But the biggest mistake I made was listening to my GC when he told me a change to the plans (pre-construction) would be "expensive". I never asked how much is "expensive". What might have been expensive to him might have been in my contingency fund. I always regretted not getting an actual number and making my decision based on fact. We still don't know if OP's contractor is watching for their actual budget or just doesn't know how to build a porch or doesn't personally like porches. My mother's contractor argued with her about putting the laundry on the first floor. He insisted the only place for a laundry was the basement! Guess who won--good job, Mother!

  • 6 years ago

    DH and I have also looked at this plan and have considered it IF we end up having to go with a 2 story home for cost reasons.

    The only person who can answer your question about the bank is....the bank ;)

    FWIW, I don't think the house will be particularly dark with all the windows.