Software
Houzz Logo Print
cookie_white30

There has to be an answer!

8 years ago

Hey everyone, I am just stumbling onto this board and am delighted! So here's our situation. We own our current home. Paid off. We had a rental property foreclosure 4 years ago but our credit is excellent. 740's. I applied through Allen Tate Mortgage and was approved for an FHA loan. Said I'd have to wait one more year for a conventional.

We have 4 kids in 1200 square feet and want to buy a larger home. We found one that we love. Very hard for us to love a house. I'm super picky about functionality and no frills and we want acreage. So, this house we found is foreclosed and was sold at auction to a 3rd party who has yet to pay for it. There is a possibility that it will go back up for auction.

The house is in disrepair, probably needing 50k to get it up to comfortable livability.

I can't buy this house with an FHA loan (needs work) we plan to sell our current home but feel it isn't wise to put all of our profits toward purchasing the house and not having a loan to fix it up.

I'd love any creative ideas you guys have on our best options!

thanks!

Comments (14)

  • 8 years ago

    Is the house livable right now, or would you have to do the work before moving in? Can you sell your current place and rent for a few months while you bring the new place up to snuff? Will you be able to pay cash for the new place with the proceeds from the sale of your current home? If so, you might be able to get a home equity line of credit or loan after you purchase the new property with cash. Lyfia's idea of a HELOC on your current home is good as well.

    Cookie thanked biondanonima (Zone 7a Hudson Valley)
  • 8 years ago

    A HELOC on our current home is out. I think it's a true 7 year wait

  • 8 years ago
    last modified: 8 years ago

    I love the idea of HELOC on the new home. Is that possible soon after purchase? I'm guessing it would have to be s refi though

  • 8 years ago

    I don't think there are any restrictions on timing as far as a HELOC goes, but that may vary state to state.

    Cookie thanked biondanonima (Zone 7a Hudson Valley)
  • 8 years ago

    You were given, some good ideas above. My only other suggestion is that different mortgage brokers or local banks "may" have some leeway in either granting an exception to the foreclosure timing. It wouldn't hurt to call around to different places with good reviews or get recommendations from friends/family and tell them your situation and get their suggestions if they have a hard 7-year requirement and if not what products they'd be able to provide you (bridge loan etc.).

    Cookie thanked Kelly
  • 8 years ago
    last modified: 8 years ago

    Kelly is right. You are currently working with a lender that has "overlays" of their own -over and above what Fanny Mae or Freddie Mac require for mortgages. Their guidelines only require 4 years from a foreclosure and not 5. Go to Guaranteed Rate - they have no overlays. Go to = online (not physically). They are a nationwide lender. They originate, underwrite and fund their own loans. There are others without overlays. Just do your research to find out which lenders can work with your criteria.

    As to rehabbing - you can also get a FHA 203k loan that allows rehabbing in the loan. It's one loan with the mortgage and rehab component in the same loan. There are detailed steps to get the loan, but they are readily available. There are corresponding conventional loans also with a rehab component. The fact that the LO didn't discuss all of these options with you shows that your current LO is not well informed (IMO) or maybe his lender doesn't have those programs. Get away from that lender and go to one that has programs that work for you

    Cookie thanked Denita
  • 8 years ago

    You guys are awesome! So there's more information now. I called the lawyer that the house is being handled by and they said the 3rd party is nearing the end of an extension period and have not paid. The lady said that if they don't pay, then the previous owner could list it back up for sale. So I'm trying to connect with the previous owner now, to ask if we can buy it from him. It's so convoluted but this house looks to be everything we want.

  • 8 years ago


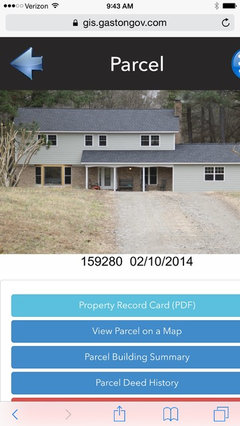
    Here's the house from the tax website

  • 8 years ago

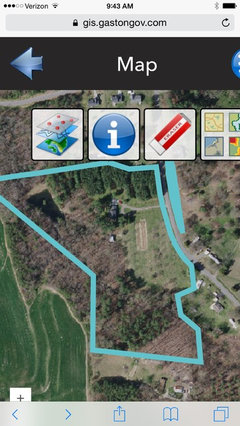
    And here's the property.

  • 8 years ago

    Cookie, Don’t you think you should have the money first then contact the lawyer and previous owner?

  • 8 years ago
    last modified: 8 years ago

    That would definitely be ideal. I think it all boils down to timing though. There are many factors to indicate that our current house will sell very quickly. We have a family of 6 with pets and cannot be homeless.

  • 8 years ago
    last modified: 8 years ago

    @Denita- in a rare postion of disagreement, I'm not a fan of 203k loans. These loans carry fairly high expense ratios in the way of all sorts of fees- jacks up APR a lot.

    @Cookie- if you haven't already done it or ignored it, go to the bank that owns it before you go to anybody else. If the 3rd party hasn't yet paid for it, then the bank is still in possession.

  • 8 years ago

    @Laurie, I agree with you about 203k loans in general. Every once in a while they make sense but for the most part they are a very expensive and time consuming way to rehab a property.